Check out our Buy to Let criteria.
At least one applicant must own and reside in their own home in the UK to be eligible for our simplified calculations.
Where the customer owns a residential home but they don’t live in this due to living in tied-accommodation as part of their employment (e.g. armed forces, boarding school teacher, vicar/minister, estate worker), this is acceptable providing the customer continues to have a residential property e.g. a property on Consent to Let.
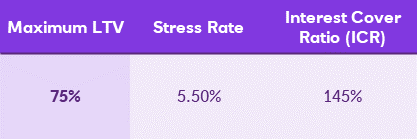
Affordability will be determined by evaluating the property to be mortgaged, using a rental income coverage ratio (ICR) and a stress rate specific to the product.

Please use our calculator to check the maximum we can lend.
Portfolio Landlords only (4 or more mortgaged Buy to Let UK rental properties, following completion of this mortgage application. All BTL properties owned individually, jointly or through a SPV / limited company (20% or more shareholding) must be taken into account, including: Consent to Let properties, Holiday lets and HMOs)
If the applicant has a Buy to Let property held within a limited company/SPV, please see Keying the application.
Where the customer is a Portfolio Landlord, we’ll assess the customer’s portfolio, including the property being purchased or remortgaged, to ensure the aggregate LTV and ICR remain sustainable.
Please note, we validate the customers estimated rent and capital on all background properties.
Where the customer is doing a Like-for-Like remortgage this check isn’t required.
We don’t allow Top Slicing on this type of application.
Portfolio landlords only - At least one applicant must have at least 2 years landlord experience.
Max Portfolio
Portfolio landlords with 10 or less Buy to Let or Consent to Let properties at completion may be considered. This includes all Buy to Let properties, whether mortgaged or unencumbered, owned personally or via SPV / limited company (20% or more shareholding), including Holiday lets and HMOs, and those owned solely or jointly.
Max age
Age 80 at the end of the term.
Your responsibilities when submitting Buy to Let applications
Enter all required information accurately and completely to support the correct lending decision and avoid delays. This includes relevant background properties, property values, mortgage details, rental income and the tax band selected.
For joint applications where customers have different tax bands, select the highest tax band.
We’ll automatically assess the customer’s tax band using the information entered and compare this with the tax band selected. The higher tax band will be used when assessing affordability. If a higher tax band is applied, check that the information entered is accurate and complete.
If the information entered is accurate, the tax band applied by the application cannot be changed or overridden.
Some applications may require income and rental evidence to be submitted for underwriter assessment. Where your DIP requests this evidence, please refer to the requirements below to confirm the documents needed.
For all other BTL applications, continue to retain supporting evidence in line with the Terms of Business. We may request this evidence as part of periodic audit checks.
Personal income
Basic employed income: one month’s payslip.
Variable employed income: three months’ payslips.
Self-employed income: follow our self-employed packaging guidance for the relevant business type and trading history.
Other income: use our Income and Packaging guidance to confirm the documents required for the relevant income type.
Rental income
Where rental-income evidence is requested, provide one month’s bank statement covering the latest 31 days for:
The property being remortgaged, where applicable.
Relevant background rental properties.
An underwriter may request additional information where needed to assess the application.
Check out our hub for First-time Buyers and Non-Owner Occupiers